TL;DR — Key Takeaways
- A coverage gap means a period of your practice history has no policy that will respond to a claim, and the consequences run in three directions at once: personal financial exposure, credentialing and privileging trouble, and contract breach.
- Gaps usually happen quietly: a missed tail election window, a retroactive-date mismatch when switching carriers, an employer’s program change, or a dissolved group that never bought wind-down coverage.
- Hospital bylaws, payer enrollment, and medical staff applications routinely require proof of continuous coverage, and they ask about gaps directly.
- A discovered gap is a manage-it-now problem: options narrow with time, and misstating coverage history on applications compounds the original problem with a worse one.
- Employers and groups share the exposure when a departed physician goes bare, which is why verification belongs in every off-boarding checklist.
The Direct Answer
A malpractice coverage gap is a stretch of your professional past that no policy will answer for. If a claim about that period arrives, there is no carrier to defend it and no policy to pay it: the defense costs and any settlement or judgment are personal. And because hospitals, payers, and employers all ask about continuous coverage, the gap keeps costing you even if no claim ever comes. The good news is that most gaps are preventable with calendar discipline, and some are fixable if caught early.
Bay Legal, PC helps California physicians and practices handle the contract and credentialing side of coverage transitions, including the departures and deals where gaps are usually born. Call (213) 668-8000 in Northern California or (213) 668-8000 in Southern California.
How Gaps Actually Happen
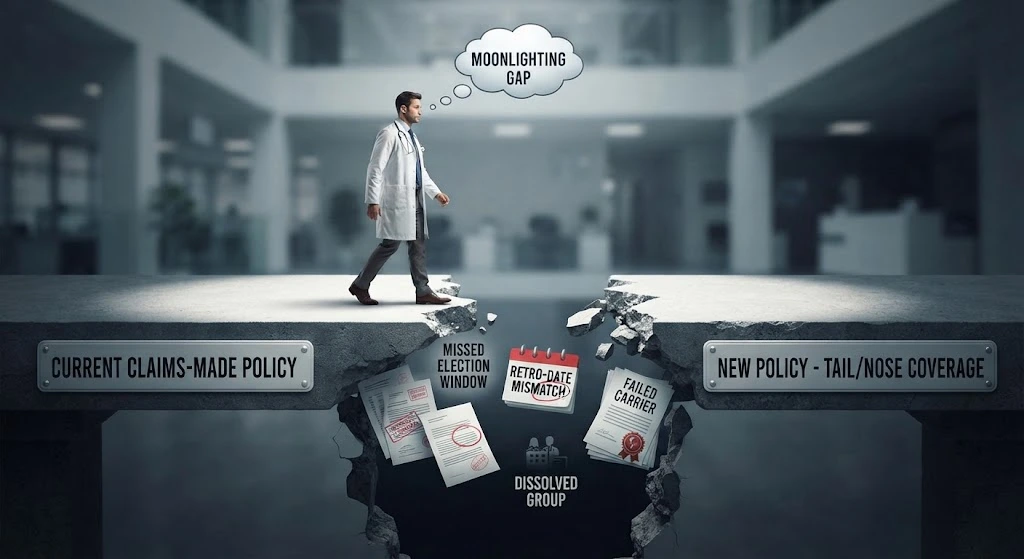
Almost no one decides to go bare. Gaps happen at transitions:
The missed election window. A claims-made policy ends, the tail quote arrives during a chaotic month, and the carrier’s deadline, commonly a matter of weeks after termination, passes unelected. The reporting rights are gone, and with them coverage for every year the policy spanned.
The retroactive-date mismatch. A physician switches carriers and relies on nose (prior acts) coverage instead of buying tail. The new policy’s retroactive date is supposed to match the old policy’s original retro date exactly. If it instead matches the new policy’s start date, or misses the true original date by a gap of any length, the years in between are uninsured. This is the quietest gap of all, because everything looks insured: there is an active policy, a certificate, a premium being paid. The hole is in a date most people never read.
The employer program change. An employer switches carriers, moves to self-insurance, or restructures mid-employment. Whether prior acts carried over is a question someone had to ask at the transition; if no one did, the answer surfaces years later.
The dissolved group. A group winds down, the entity policy is cancelled, and no wind-down tail is purchased for the entity or arranged for the departed physicians. Everyone assumes someone else handled it.
The moonlighting gap. Side work is its own coverage universe. A physician fully insured through an employer picks up telehealth shifts, weekend urgent-care work, or medical-director duties outside the employer’s program, assuming the day-job policy reaches them. Employer policies typically cover services rendered for the employer; the side work needs its own coverage, and if that side coverage is claims-made, it eventually needs its own tail. The gap here is double: uninsured activity in real time, and no reporting rights later.
The disputed departure. The physician and the former employer disagree about who owes the tail, the argument outlasts the election window, and the gap becomes permanent while the emails continue. Our post on termination and severance covers why the coverage must be protected first and the allocation fought second.
The failed carrier. Rarer, but real: a carrier or coverage vehicle becomes insolvent, and depending on what stands behind it, the tail obligations may not be fully protected. Ask what backs the paper, particularly with non-traditional coverage vehicles.
Cost One: Personal Exposure
If a claim lands in the gap, you are the insurance company. That means funding your own defense, lawyers, experts, years of litigation, and personally bearing any settlement or judgment. California caps non-economic damages in professional negligence cases, with caps that rise annually under current law, but economic damages, the medical costs and lost earnings that drive large verdicts, are not capped at all. A physician’s savings, investment assets, and future income are all in the conversation, and a malpractice judgment is not the kind of debt that quietly goes away.
It is worth saying plainly: the premium that felt expensive at the transition is, in every gap scenario, the cheapest number in the story.
Cost Two: Credentialing, Privileges, and Enrollment
The second cost arrives even if no claim ever does.
Hospital medical staff bylaws typically require members to maintain professional liability coverage at specified limits, continuously, and to disclose lapses. Credentialing and re-credentialing applications ask directly about coverage history, gaps, and carrier terminations. Payer enrollment and delegated credentialing processes ask their own versions. A gap turns each of those forms into a problem: disclose it and expect questions, conditions, or worse; misstate it and create a dishonesty issue that outlives the gap and can threaten privileges and licensure in ways a coverage lapse alone never would.
The rule for applications is absolute honesty, paired with a proactive explanation. Credentialing committees deal with explainable transitions all the time; what they do not forgive is discovering one you papered over.
If a gap has already surfaced in a credentialing or privileging process, get advice before responding. Bay Legal, PC works with California physicians on the legal side of these situations. Reach us at baylegal.com/contact, or call (650) 668-8000 or (213) 668-8000.
Cost Three: Contract Breach
Physician employment agreements, group buy-sells, and practice purchase agreements routinely include continuous-coverage covenants: the physician will maintain coverage, including tail where applicable, at stated limits. Letting coverage lapse can breach those obligations, giving a former employer, a group, or a buyer its own claim against you, and it strips you of the indemnification and cooperation posture you would want if a shared claim arrives. In deals, a seller’s coverage gap discovered post-closing tends to become an indemnification fight; in employment, a departed physician’s gap tends to become everyone’s problem, which is the next point.
The Shared-Exposure Point: Why Groups Verify
Claims about a physician’s care rarely name only the physician. The group, the entity, and supervising structures are usually named too. When the departed physician has no coverage, the shared defense degrades: the uninsured defendant has no carrier-funded counsel, settlement dynamics tilt, and contractual indemnity against the physician is only as good as the physician’s balance sheet. Well-run practices therefore verify a departing physician’s tail the way they verify the return of the badge and the laptop: certificate in hand, deadline calendared, before the severance check releases. Our group-policy companion post covers the group-side mechanics.
If You Discover a Gap: Triage
A discovered gap is time-sensitive. In rough order:
- Reconstruct the record. Pull every policy, declarations page, and certificate for the affected years. Confirm the gap is real; apparent gaps sometimes dissolve when the actual retro dates and tail endorsements are located.
- Call the broker, quickly. Depending on how recent the lapse is, options may exist: some carriers will reinstate or backdate in narrow circumstances, and specialty markets sometimes write retroactive or gap-specific coverage. Availability shrinks as time passes, and none of it is guaranteed; move now rather than after the next renewal.
- Get legal advice before the forms. If credentialing, enrollment, or an application cycle is imminent, sequence the fix and the disclosure deliberately, and answer every question truthfully.
- Check the contracts. Identify any continuous-coverage covenants implicated and whether notice or cure provisions apply.
- Preserve the allocation claims. If someone else was contractually obligated to buy the coverage, protect yourself first and pursue the reimbursement second.
The pattern in every good outcome is the same: the physician moved early, told the truth, and treated the gap as a project instead of a secret.
Coverage gaps sit exactly where insurance questions become legal ones, contracts, credentialing, deals, and disputes. If one is on your desk, Bay Legal, PC can help. Call (650) 668-8000 (Northern California) or (213) 668-8000 (Southern California), or contact us at baylegal.com/contact.
Frequently Asked Questions
What does “going bare” mean for a physician?
Practicing, or carrying a past period of practice, without malpractice coverage that will respond to a claim. For that period, defense costs and any judgment are personal, and continuous-coverage requirements in bylaws and contracts may be breached.
Can a malpractice coverage gap affect my hospital privileges?
Yes. Bylaws and credentialing processes typically require continuous coverage at stated limits and ask about lapses directly. A gap can trigger questions, conditions, or adverse action, and a misstatement about it is generally a more serious problem than the gap itself.
Can a coverage gap be fixed after the fact?
Sometimes, and the odds improve the faster you act. Recent lapses can occasionally be reinstated or backdated, and specialty markets sometimes write retroactive coverage in narrow circumstances. None of this is guaranteed; treat a discovered gap as urgent.
What is a retroactive-date mismatch?
When replacement coverage is supposed to reach back to your original retroactive date but was issued with a later one, leaving the years in between uninsured despite an active policy. It is among the most common quiet gaps; check the retro date on every new policy against your true original date.
Who is responsible if my employer was supposed to buy my tail and didn’t?
The contract allocates the cost, and you may well have claims, but the exposure in the meantime is yours. Protect the coverage first, within the carrier’s election window if it is still open, and pursue the contractual allocation second.