TL;DR — Key Takeaways
- Tail coverage comes in fixed terms, commonly one, two, three, or five years, and in unlimited form. The right duration depends on how long a patient can still sue, which in California is governed by Code of Civil Procedure section 340.5.
- California’s basic rule gives a malpractice plaintiff three years from the injury or one year from discovering it, whichever comes first, but the exceptions are what matter for tail planning.
- Tolling for fraud, intentional concealment, and retained foreign objects can extend the outer limit, and claims involving young children can arrive years later; a fixed-term tail can expire while a lawful claim is still possible.
- Unlimited tail costs more up front, but it is the only duration that cannot be outrun.
- Employment agreements and purchase agreements sometimes specify short minimum tail terms; treat those as floors to scrutinize, not answers to rely on.
The Direct Answer
The honest answer to “how long should my tail last” is: at least as long as someone can lawfully bring a claim about your care, plus the time it takes such a claim to actually arrive on your doorstep. In California, that period is usually measured by section 340.5, and its exceptions make the true outer edge longer and fuzzier than the headline rule suggests. That fuzziness is the argument for unlimited tail, and it is why brokers and physician advisers so frequently land there despite the higher premium.
Bay Legal, PC advises California physicians and practice owners on the contracts and transactions where tail duration gets decided, often years before anyone tests it. Call (650) 668-8000 in Northern California or (213) 668-8000 in Southern California.
The Durations Carriers Sell
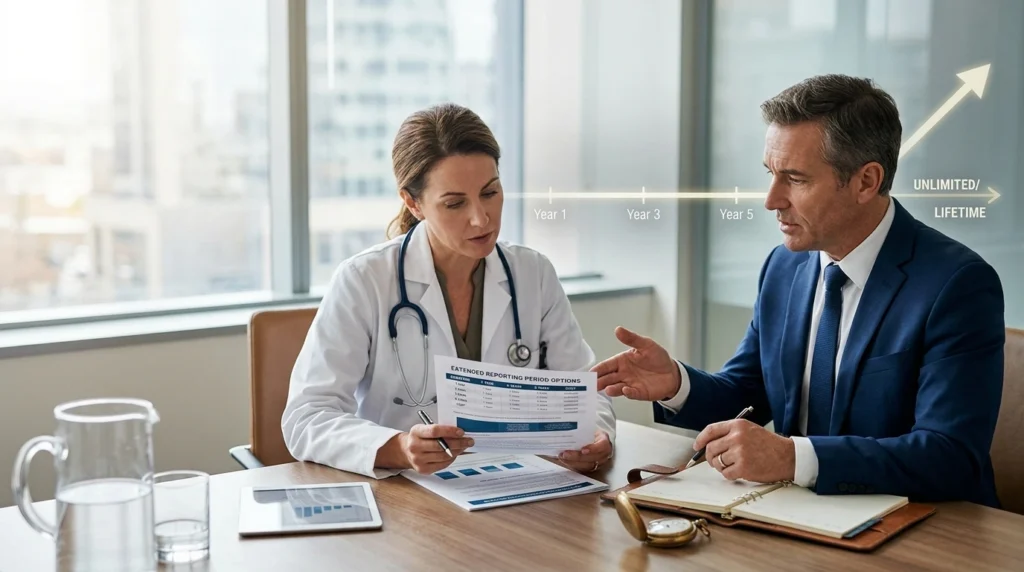
When a claims-made policy ends, carriers typically quote tail in a menu of terms: one year, two, three, five, and unlimited (sometimes called a full or lifetime tail). Shorter terms cost less; the discount is real and, for a physician writing a five-figure check in the same month a job ends, tempting.
The mechanics to keep straight: a five-year tail means claims must be first made and reported within five years after the policy terminated, for care during the policy period. On day one of year six, the window closes, whatever the merits, and whatever the statute of limitations still allows.
So the duration question reduces to a comparison: the tail’s reporting window versus the law’s filing window. When the second is longer than the first, the physician is bare for the difference.
California’s Filing Window: The Section 340.5 Baseline
California’s statute of limitations for professional negligence against health care providers runs, as of drafting, on a dual trigger: the earlier of three years from the date of injury, or one year from the date the patient discovers, or reasonably should have discovered, the injury. There is also a procedural wrinkle worth knowing: a plaintiff who serves the required pre-suit notice in the final ninety days of the limitations period effectively gains an extension to file.
Read casually, that sounds like a three-year problem, which makes a three-year tail sound adequate. Two things break that comfort.
First, the clock runs from injury and discovery, not from your last day of work. A tail’s term runs from policy termination. The statute runs from events in the patient’s life. Care you provided in your final month of employment can be discovered late in the third year afterward, generating a claim that is timely under the statute but arrives near, or past, the edge of a short tail.
Second, the exceptions. The three-year outer limit is tolled in defined circumstances, including fraud, intentional concealment, and the presence of a non-therapeutic foreign object left in the patient. And for young children the rules differ: claims for minors under six can generally be brought within three years or before the child’s eighth birthday, whichever is longer, which for birth-related care creates an exposure window measured in many years, not months. These are precisely the claims that surface long after everyone has moved on, and precisely the ones a short tail misses.
Every period in this section is stated as of drafting and simplified; limitations analysis is fact-specific, and tolling questions are exactly the kind of issue that requires advice on real facts.
Illustrative Timelines: Where Fixed Terms Break
Two hypotheticals, both illustrative rather than predictions:
The late-discovery claim. A physician leaves a practice in June and buys a three-year tail. Care from that final spring involves a missed finding a patient has no reason to suspect. The patient discovers the problem thirty months later and, within the one-year discovery window, makes a claim thirty-nine months after the physician’s departure. Timely under the statute. Three months past the tail.
The pediatric claim. A physician’s claims-made policy covers obstetric care. A child injured at birth can, under the minor-tolling rules, generate a claim years down the road. A five-year tail can be outlived by a kindergartner.
Neither scenario requires bad luck of any exotic kind. They require only the ordinary operation of California’s discovery and tolling rules against a calendar that stopped counting.
If you are choosing a tail term as part of a departure, a practice sale, or a retirement, the duration decision deserves the same attention as the who-pays decision. Bay Legal, PC can help you think through both in the contract where they live. Reach us at baylegal.com/contact, or call (650) 668-8000 or (213) 668-8000.
Why Unlimited Is the Frequent Default Recommendation
An unlimited tail cannot be outrun. That is its entire argument, and for most physicians it is sufficient. The exposure a tail protects against is asymmetric: the premium difference between a five-year and an unlimited tail is bounded and known; the cost of one uninsured claim is neither. California’s cap on non-economic damages, which rises annually under current law, does not cap economic damages at all, and defense costs alone can be substantial. Physicians in specialties with long-latency claims, obstetrics, pediatrics, surgery with implanted devices, radiology, have the strongest case of all, but the logic reaches further than the obvious specialties.
There are situations where a shorter term gets chosen anyway: a physician paying personally under a contract that only requires a shorter term, an employer satisfying a bare contractual minimum, a deal where the parties split the difference on cost. Understand those for what they are: allocations of a known risk to whoever holds the gap. If a contract you are negotiating specifies tail duration, treat a short term as a red flag to price, not boilerplate to accept. Where the burden falls on you, the question to ask is who bears the claim that arrives in year six.
The Contract Layer: Minimums Are Not Advice
Tail duration usually gets fixed in one of three documents: an employment agreement, a severance agreement, or a purchase agreement. Each has a habit worth correcting:
- Employment agreements sometimes require “tail coverage” without a stated duration, which invites the cheapest compliant purchase. Specify the term.
- Severance agreements written in a hurry often adopt whatever the carrier quotes first. Get the unlimited quote alongside the fixed-term quotes before agreeing.
- Purchase agreements in practice sales should match the tail term to the real post-closing exposure window, including entity wind-down timelines, rather than to a round number. Our practice-sale pillar covers that allocation.
In each case, the number that matters is the one in the signed document. A broker can price the options; the contract decides who pays and what counts as compliance.
One further habit closes the loop: when someone else buys your tail, an employer under a severance term, a practice under a purchase agreement, verify the duration on the endorsement itself, not the cover email. A tail purchased at the wrong term still generates a certificate, a confirmation, and a sense of completion; the difference between the five-year tail that was bought and the unlimited tail that was promised surfaces only when a late claim arrives. Read the endorsement, match it to the contract, and keep both. It is a five-minute task that removes a failure mode nobody catches at the time.
Tail duration is one of the few insurance decisions that is genuinely hard to fix later: once the election window closes, the menu is gone. If the decision is in front of you now, Bay Legal, PC can help you get the contract side right. Call (650) 668-8000 (Northern California) or (213) 668-8000 (Southern California), or contact us at baylegal.com/contact.
Frequently Asked Questions
Is a three-year tail enough in California?
Often it is not the safe answer. California’s basic limitations rule pairs a three-year outer limit with a one-year discovery trigger, and tolling rules for concealment, foreign objects, and minors can push claims later still. A timely claim can arrive after a three-year tail has expired. The analysis is fact-specific; treat any fixed term as a decision to be priced, not a default.
What does unlimited tail coverage mean?
An unlimited (or full) tail has no expiration on the reporting window: a covered claim about care during the original policy period can be reported whenever it arrives. It costs more than fixed terms and is the only duration that cannot be outlived by a late claim.
How long do patients have to sue for malpractice in California?
As of drafting, generally the earlier of three years from the injury or one year from its discovery, with defined tolling exceptions (including fraud, concealment, and retained foreign objects) and special rules for young children. The rules are technical and fact-specific; this is general information, not an assessment of any particular claim.
Why do claims about children arrive so much later?
California’s rules for minors differ from the adult rule; claims for children under six can generally be brought within three years or before the child’s eighth birthday, whichever is longer. Birth-related care therefore carries one of the longest exposure windows in malpractice, which matters when choosing tail duration for obstetric or pediatric practice.
Can I add more tail later if I chose a short term?
Generally not easily. Tail elections run on short carrier deadlines around policy termination, and extending or repurchasing after the fact ranges from expensive to unavailable. The realistic moment to get duration right is at the election.