TL;DR — Key Takeaways
- How to start a nonprofit in California means satisfying three regulators, not one. The Secretary of State takes the articles, the Attorney General maintains the Register of Charitable Trusts, and the Franchise Tax Board and IRS handle exemption. Each has its own filing, its own deadline and its own consequence for missing it.
- Corporations Code section 5130 tells you exactly what the articles must say, including a statement quoted word for word in the statute. It does not require a dissolution clause. Revenue and Taxation Code section 23701d does, for the state exemption – so the two lists are different and the articles that satisfy the Corporations Code can still sink the exemption application.
- Attorney General registration is due within 30 days after the organization first receives property, under Government Code section 12585 – not within 30 days of incorporating, and not when you start fundraising.
- At $2,000,000 of gross revenue – the statutory threshold as of drafting – three obligations switch on at once: an independent CPA audit under generally accepted auditing standards, public availability of the audited statements within nine months of year end, and a board-appointed audit committee that may not include the CEO or CFO.
- Churches, schools and hospitals are largely outside the Attorney General’s filing regime under Gov. Code section 12583. That exemption is broader than most guidance suggests and is worth checking before you register.
The Direct Answer
Form a nonprofit public benefit corporation by filing articles that satisfy Corporations Code section 5130, add the asset-dedication language Revenue and Taxation Code section 23701d requires, register with the Attorney General within 30 days of first receiving property, and apply for exemption federally and with the Franchise Tax Board.
How to Start a Nonprofit in California: The Articles Are Not the Finish Line
The formation step is short. Under Corporations Code section 5120 one or more persons form the corporation by filing articles; if initial directors are named each must sign and acknowledge them, and if none are named the signers are the incorporators. Corporate existence begins on filing.
Section 5130 says what the articles must set forth: the name; the statutory purpose statement; the initial agent for service of process with a California street address; the initial street address; and the initial mailing address if different. The purpose statement is not paraphrasable, because the statute prints it: “This corporation is a nonprofit public benefit corporation and is not organized for the private gain of any person. It is organized under the Nonprofit Public Benefit Corporation Law for (public or charitable [insert one or both]) purposes.” The bracketed instruction is the statute’s own. If the purposes include “public” purposes, the articles shall include a further description; in all other cases they may.
Here is the trap, and it is structural rather than a drafting slip. Section 5130 contains no requirement that the articles dedicate the corporation’s assets irrevocably to exempt purposes or say where they go on dissolution. Revenue and Taxation Code section 23701d contains exactly that requirement: an organization “is not organized exclusively for exempt purposes listed above unless its assets are irrevocably dedicated to one or more purposes listed in this section,” and dedication requires that on dissolution, or the impossibility of performing the specific organizational purposes, the assets continue to be devoted to exempt purposes. The statute deems that satisfied where the articles say the assets go on dissolution to an organization exempt under section 23701d or Internal Revenue Code section 501(c)(3), or to a federal, state or local government for public purposes.
Two statutes, two different lists, and only one is enforced at the counter. Articles drafted to the section 5130 minimum will file cleanly and then fail the exemption test. That is why, for 501c3 california requirements, the sequencing matters more than the paperwork: fix the articles before you apply, because the Franchise Tax Board and the IRS both read them. Federal recognition under Internal Revenue Code section 501(c)(3) is a separate application, and no processing time is asserted in this article – published figures change and differ between the long-form and streamlined versions, so get the current one from the IRS or counsel.
Two smaller points. Section 5122 requires the Commissioner of Financial Protection and Innovation’s certificate of approval for a name including “bank,” “trust” or “trustee,” and limits a name reservation to 60 days with no consecutive reservations. And section 5120(d) provides that at the time of filing the Secretary of State makes the articles available to the Attorney General – the charitable regulator knows the organization exists before it registers.
One route in is easy to miss. Corporations Code section 13406(b) allows a professional law corporation to be incorporated as a nonprofit public benefit corporation – either as a qualified legal services project or support center under Business and Professions Code section 6213, or on four conditions: all members and all directors licensed to practice law in California, 70 percent of clients being lower income persons as defined in Health and Safety Code section 50079.5 or persons who would not otherwise have access to legal services, and no contingency fee contracts.
What Must Be Registered With the California Attorney General?
This is where California differs most from what generic guidance describes, and the answer starts with who is exempt.
Government Code section 12583 provides that the filing, registration and reporting provisions do not apply to government entities and their subdivisions; to “any religious corporation sole or other religious corporation or organization that holds property for religious purposes”; to a cemetery corporation regulated under the Business and Professions Code; to a political committee filing under the Political Reform Act; “or to a charitable corporation or unincorporated association organized and operated primarily as a religious organization, educational institution, hospital, or a health care service plan” licensed under Health and Safety Code section 1349.
Read that clause again if you run a school or a hospital. It is broad, statutory, and removes the whole filing regime rather than a single form.
For everyone else, section 12581 puts the organization inside the Supervision of Trustees and Fundraisers for Charitable Purposes Act, which since January 1, 2023 expressly reaches charitable fundraising platforms and platform charities as well as charitable corporations, trustees and commercial fundraisers.
The initial filing is section 12585: a registration form, under oath, “within 30 days after the corporation, unincorporated association, or trustee initially receives property.” Two things follow. The clock starts on receipt of property, not on incorporation and not on first solicitation. And a trustee holding only a future charitable interest need not register until it becomes a present one, and then has 30 days. Section 12584 explains the purpose: the office maintains a register of charitable corporations, associations and trustees and may gather records to keep it current.
For nonprofit registration california attorney general purposes the rule is short: register when the property arrives, keep it current, and answer deficiency letters fast – section 12586.1 charges a fee for failing to correct deficiencies within 10 days of written notice.
What Annual Filings and Board Requirements Apply?
Three annual or biennial obligations, on three different clocks, plus a set of board rules that apply regardless of size.
| Filing | Authority | When |
|---|---|---|
| Attorney General periodic report | Gov. Code Sec. 12586(d) | First report no later than four months and 15 days after the close of the first calendar or fiscal year in which property is initially received, and annually thereafter |
| Attorney General registration/renewal | Gov. Code Sec. 12586.1(e) | Within the time the Attorney General specifies, irrespective of other report filing requirements |
| Franchise Tax Board annual return | Rev. & Tax. Code Sec. 23772(a)(1) | On or before the 15th day of the fifth full calendar month following the close of the taxable year |
| Secretary of State statement of information | Corp. Code Sec. 6210(a) | Within 90 days after filing the original articles, and biennially thereafter |
Two details inside that table do real work. The Franchise Tax Board return has mandatory exceptions under section 23772(a)(2)(A): churches, their integrated auxiliaries and conventions or associations of churches; the exclusively religious activities of a religious order; and an organization other than a private foundation “the gross receipts of which in each taxable year are normally not more than fifty thousand dollars ($50,000).” Those thresholds are the figures as of drafting. And the statement of information is biennial, not annual, with section 6210(c) setting the filing period as the month the original articles were filed plus the five preceding months – and the statute is blunt about the reminder: neither the Secretary of State’s failure to send the notice nor the corporation’s failure to receive it “is an excuse for failure to comply.”
Four Corporations Code rules decide most questions about nonprofit board requirements california organizations face:
- Section 5210: the corporation shall have a board, and its activities and affairs shall be conducted and all corporate powers exercised by or under the direction of the board. Management may be delegated, but only so that the affairs are managed “under the ultimate direction of the board.”
- Section 5211: meetings may be called by the chair, the president, any vice president, the secretary or any two directors. Special meetings require four days’ notice by first-class mail or 48 hours’ notice personally, by telephone or by electronic transmission – and “the articles or bylaws may not dispense with notice of a special meeting.” Remote participation counts as presence in person if all participating directors can hear one another.
- Section 5212: a board committee consists of two or more directors and may exercise the board’s authority except for eight enumerated matters, including filling vacancies, fixing director compensation, amending the bylaws and approving a self-dealing transaction. A committee exercising board authority may not include non-directors, though the board may create other committees that do not.
- Section 5227: not more than 49 percent of the persons serving on the board may be interested persons – anyone currently compensated by the corporation for services within the previous 12 months, excluding reasonable compensation paid to a director as director, plus a defined list of that person’s relatives.
Section 5227 has a subdivision that changes how you fix a violation. Subdivision (d) provides that the section “shall not affect the validity or enforceability of any transaction entered into by a corporation” – so exceeding 49 percent does not void the board’s contracts. It exposes the composition to a court order under subdivision (c), which may direct the election of additional directors, enlarge the board, or remove directors.
Self-dealing is section 5233, and its numbers matter. It reaches a transaction in which a director has a material financial interest and which meets no statutory safe harbour. One useful exclusion: a transaction the interested director has no actual knowledge of and which does not exceed the lesser of 1 percent of the corporation’s gross receipts for the preceding fiscal year or $100,000, figures current as of drafting. The safe harbour that matters requires all four of – the corporation entered the transaction for its own benefit; it was fair and reasonable at the time; the board approved it in good faith before consummation by a majority of directors then in office, without counting the interested director and with knowledge of the material facts; and the board determined after reasonable investigation that no more advantageous arrangement was available.
And the limitations periods are asymmetric. Two years after written notice of the material facts is filed with the Attorney General, or three years from the transaction if no notice was filed – “except for the Attorney General, who shall have 10 years after the transaction occurred within which to file an action.”
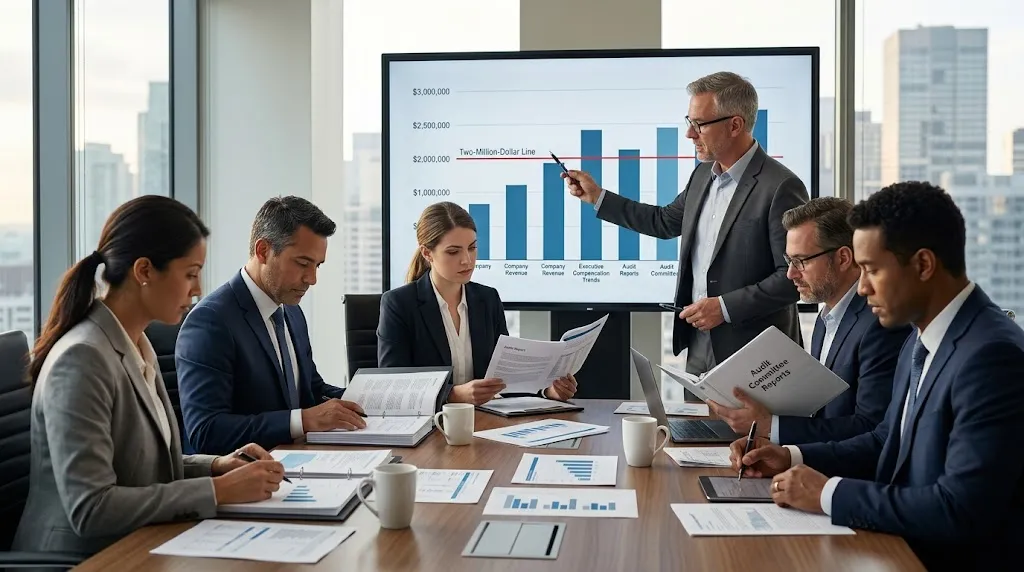
Government Code section 12586(e) is the largest single compliance step a growing California nonprofit takes, and it arrives all at once.
The threshold is gross revenue of $2,000,000 or more received or accrued in any fiscal year, “exclusive of grants from, and contracts for services with, governmental entities for which the governmental entity requires an accounting of the funds received” – a carve-out that can keep a substantially larger organization below the line. Above it, three obligations:
- An audit. Annual financial statements prepared using generally accepted accounting principles and audited by an independent certified public accountant in conformity with generally accepted auditing standards, with the firm and its auditors adhering to the auditor-independence standards in the Government Auditing Standards – the Yellow Book – for any nonaudit services.
- Publication. The audited statements must be available for inspection by the Attorney General and by members of the public no later than nine months after the close of the fiscal year, and made public in the same manner prescribed for IRS Form 990 by Internal Revenue Code section 6104(d). Subdivision (f) extends the same duty to an organization audited voluntarily.
- An audit committee, appointed by the board, with unusually specific composition rules: it may include persons who are not directors, but may not include any members of staff, “including the president or chief executive officer and the treasurer or chief financial officer.” It must be separate from any finance committee; finance members may serve but the audit chair may not be one, and finance members must be less than one-half of the committee. Members may not be paid beyond what directors receive for board service, or hold a material financial interest in an entity doing business with the corporation. Subject to board supervision it recommends retention and termination of the auditor, may negotiate the auditor’s compensation, decides whether to accept the audit, and approves any nonaudit services.
Subdivision (g) applies at every size and is the most commonly missed provision in this article. The board, or an authorized committee of it, must review and approve the compensation, including benefits, of the president or CEO and the treasurer or CFO “to ensure that it is just and reasonable” – on hiring, whenever the term of employment is renewed or extended, and whenever the compensation is modified, unless the modification extends to substantially all employees.
When Does a Nonprofit Risk Losing Exempt Status?
Two different things get lost, by two different regulators, and conflating them is the most common error in this area.
Registration is the Attorney General’s. Government Code section 12598(e)(1) provides that the Attorney General “may refuse to register or may revoke or suspend the registration” of a charitable corporation, trustee, commercial fundraiser, fundraising counsel, coventurer, charitable fundraising platform or platform charity found to have violated or to be operating in violation of any provision of the article, subject to Administrative Procedure Act rights. Before that point, section 12586.1 imposes $25 for each month or part of a month of delinquency, a figure current as of drafting, on triggers that include operating in California without being registered, soliciting contributions without being registered or bonded, missing the annual report deadline without an extension, missing the registration renewal, and failing to correct deficiencies within 10 days of written notice.
Exemption is the Franchise Tax Board’s and the IRS’s, and it turns on the substantive tests – exclusive exempt purpose, no private inurement, no substantial lobbying, no campaign intervention, irrevocable dedication of assets. Losing registration does not withdraw an exemption, and holding an exemption does not excuse a registration failure.
Section 12598 also carries a consequence directors should hear before they join a board. Subdivisions (b) and (c) entitle the Attorney General to recover from defendants in a charitable trust enforcement action “all reasonable attorney’s fees and actual costs,” including auditors, consultants and experts, paid “by the charitable organization and the individuals named as defendants in or otherwise subject to the action, in a manner that the court finds to be equitable and fair.” The exposure is not limited to the entity. Subdivision (d) is the counterweight: a suit the court finds frivolous or brought in bad faith can cost the Attorney General the charity’s costs.
Against that, section 5231 is the director’s protection and it is real. A director must act in good faith, in a manner the director believes to be in the best interests of the corporation, “and with such care, including reasonable inquiry, as an ordinarily prudent person in a like position would use under similar circumstances,” and may rely on officers and employees believed reliable and competent, on counsel and independent accountants within their competence, and on a committee the director does not serve on. A director who meets that standard has no liability for an alleged failure to discharge the office – including, in the statute’s words, for “any actions or omissions which exceed or defeat a public or charitable purpose” – except for self-dealing.
When to Bring Counsel In
At the articles, and again at two million dollars.
The articles are the cheapest moment, because the section 5130 statement and the section 23701d dedication language must coexist in one document two governments will read. The second is when revenue approaches $2,000,000, because the audit, the publication duty and the audit committee arrive together and the committee has composition rules most existing boards do not satisfy. In between, the events worth a call are a transaction involving a director, because section 5233’s safe harbour has to be built before the transaction rather than reconstructed after it; a compensation decision for the CEO or CFO under section 12586(g); and any deficiency letter, because the window is 10 days.
Adjacent questions are covered separately: how a charitable trust is used in a California estate plan, what a registered agent actually does, what the statement of information requires, whether the organization also needs a local business license, how entity choice changes what an organization owes, what dissolving an entity involves, the doctrine and the statute behind personal liability, and when an Attorney General enforcement action becomes a real risk.
Work with Bay Legal
Bay Legal, PC advises California nonprofits and their boards on formation and articles drafting, Attorney General registration and reporting, self-dealing and board composition questions, and the audit and audit committee obligations that arrive with growth. If you are forming an organization, or a deficiency notice or a director transaction has raised a question, call (650) 668-8000 in Northern California or (213) 668-8000 in Southern California, or schedule a consultation at https://baylegal.com/contact-us/.
Frequently Asked Questions
How do I start a nonprofit corporation in California?
File articles that satisfy Corporations Code section 5130 – the name, the statutory purpose statement the statute prints, the initial agent for service of process with a California street address, and the initial street and mailing addresses. Corporate existence begins on filing. Add the asset-dedication language Revenue and Taxation Code section 23701d requires, because section 5130 does not and the exemption depends on it. Register with the Attorney General within 30 days of first receiving property.
What is required for 501(c)(3) recognition and how long does it take?
Federal recognition is an IRS process under Internal Revenue Code section 501(c)(3), and this article states no processing time – published figures change and differ between the long-form and streamlined applications, so get the current number from the IRS or counsel. The California exemption runs through Revenue and Taxation Code section 23701d: organized and operated exclusively for the listed purposes, no private inurement, no substantial lobbying, no campaign intervention, and assets irrevocably dedicated to exempt purposes.
What must be registered with the California Attorney General?
An initial registration form, under oath, within 30 days after the organization initially receives property, under Government Code section 12585 – the clock runs from receipt of property, not from incorporation or first solicitation. Periodic reports follow under section 12586. Check section 12583 first, because its exemptions are broad: they remove the filing, registration and reporting provisions for government entities, religious organizations holding property for religious purposes, certain cemetery corporations, and any charitable corporation organized and operated primarily as a religious organization, educational institution, hospital or licensed health care service plan.
What annual filings and board requirements apply?
Three filings on three clocks: the Attorney General report four months and 15 days after fiscal year close, the Franchise Tax Board return by the 15th day of the fifth full calendar month after the taxable year closes, and the statement of information biennially. On governance, section 5210 vests the affairs in the board under its ultimate direction, section 5211 sets meeting and notice rules the bylaws cannot use to dispense with special-meeting notice, and section 5227 caps interested persons at 49 percent of the board.
When does a nonprofit risk losing exempt status?
Distinguish the two things that can be lost. Attorney General registration can be refused, suspended or revoked under Government Code section 12598(e)(1) for violating the charitable supervision article, with a $25 monthly delinquency fee under section 12586.1 before that point. Tax exemption is separate and belongs to the Franchise Tax Board and the IRS, turning on exclusive exempt purpose, no inurement, no substantial lobbying, no campaign intervention and irrevocable dedication of assets.